
 Ammar Sabilarrohman
The 2026 Franchisee Crisis: Meritage Hospitality Group Files for Chapter 11 Amidst Margin Erosion
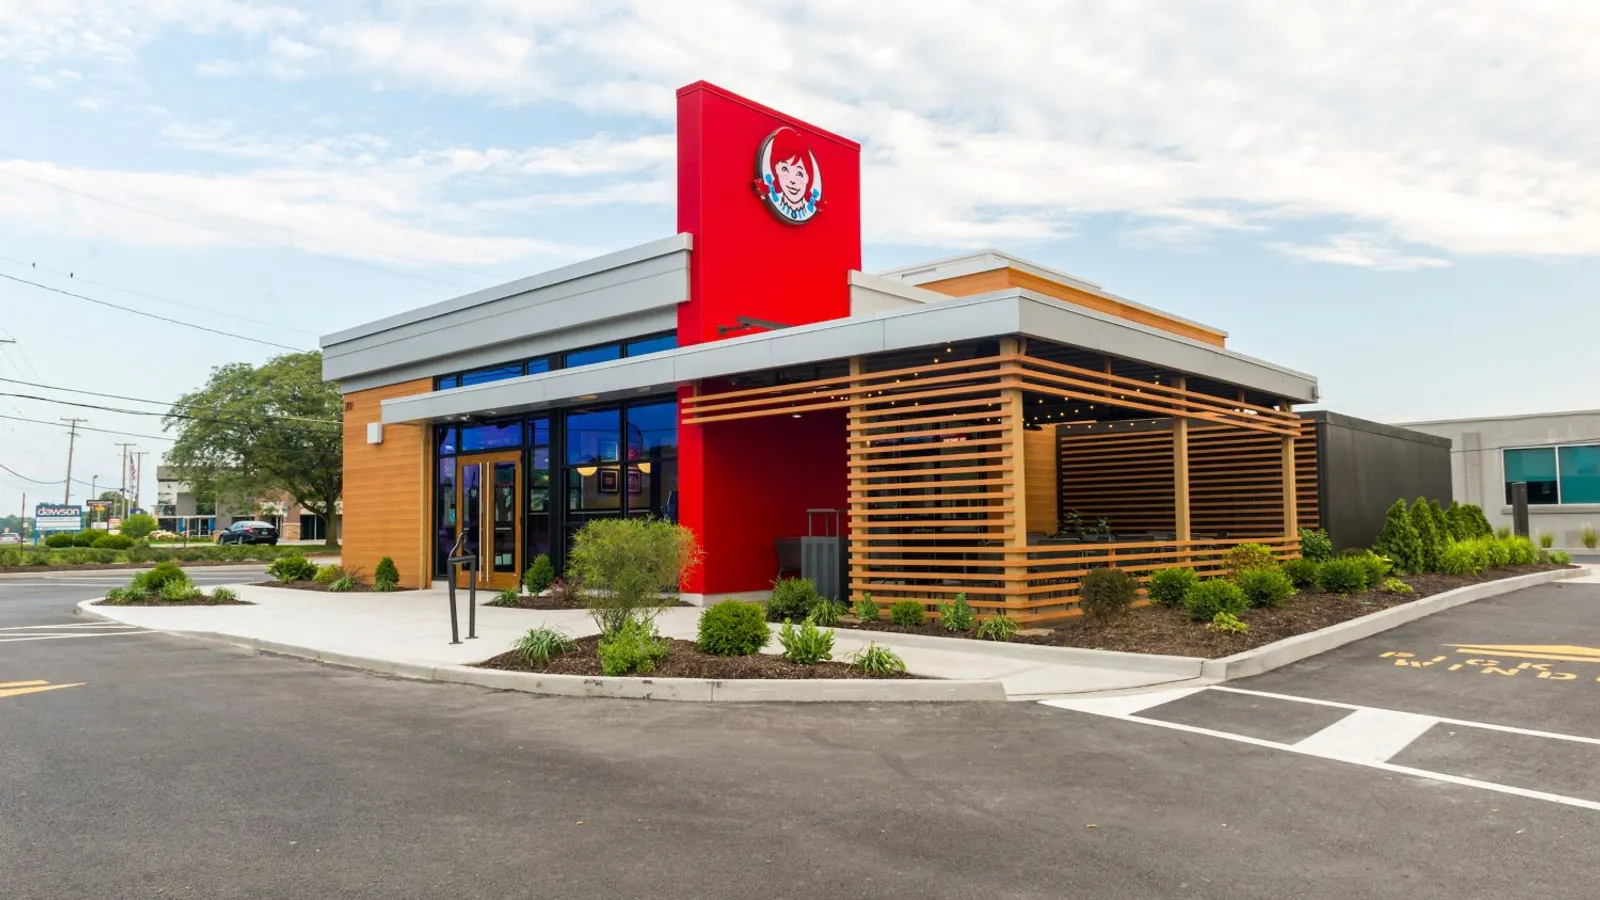
GRAND RAPIDS, MI – In a move that has sent ripples through the quick-service restaurant (QSR) sector, Meritage Hospitality Group, one of the nation’s largest and most prominent Wendy’s franchisees, has officially filed for voluntary Chapter 11 bankruptcy protection. The filing, announced on September 18, 2026, marks a significant turning point for the hospitality giant, which currently operates a portfolio of 314 Wendy’s units across several states.
The restructuring comes after a tumultuous year characterized by "30-year low" margins, a dramatic pullback in consumer discretionary spending, and a brutal inflationary environment that has decimated store-level profitability. As part of its recovery strategy, Meritage has already shuttered 60 underperforming locations and taken the drastic step of opting out of Wendy’s signature breakfast daypart in nearly 40% of its remaining fleet—a move once considered unthinkable within the Wendy’s franchise system.
Main Facts: A Giant in Transition
Meritage Hospitality Group’s bankruptcy filing is not merely a corporate restructuring; it is a symptom of a broader "Franchisee Winter" that has plagued the industry throughout 2026. The core facts of the filing highlight the severity of the situation:
- Operational Footprint: At the time of filing, Meritage oversaw 314 Wendy’s locations.
- Mass Closures: The company has already executed the closure of 60 underperforming units to stop the "bleeding" of capital.
- Profitability Collapse: Store-level EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) plummeted by 48% over the last fiscal cycle.
- The Breakfast Retreat: In an effort to save $11 million in immediate EBITDA margin, Meritage exited or significantly altered the breakfast daypart in approximately 120 locations.
- Cost-Cutting Measures: The group has slashed over $7 million from its general and administrative (G&A) expenses through aggressive internal restructuring.
The filing aims to provide the company with the "breathing room" necessary to renegotiate debt obligations with lenders and realign its operational costs with the current economic reality of the mid-2020s.
Chronology: The Road to Restructuring
The path to Chapter 11 was paved with a series of escalating macroeconomic challenges that began in the wake of the post-pandemic recovery.
2024–2025: The Inflationary Creep
Following the initial stabilization after the COVID-19 pandemic, the restaurant industry faced a secondary wave of economic pressure. Beef prices began a steady, upward climb due to supply chain disruptions and environmental factors affecting cattle yields. For a brand like Wendy’s, which anchors its identity on "fresh, never frozen" beef, these commodity spikes were particularly damaging.
Early 2026: The Forbearance Phase
By the beginning of 2026, Meritage’s financial health had reached a critical juncture. A May CEO report revealed that franchise store-level margins had hit a 30-year low. This forced the company to enter into constructive dialogues with its lenders. Meritage initially asked for and received a period of forbearance. By the second quarter of 2026, the company managed to resume full interest payments, but the underlying structural issues—high labor costs and cooling consumer demand—remained unaddressed.
Summer 2026: Aggressive Optimization
Throughout the summer of 2026, Meritage leadership attempted to course-correct without court intervention. This period saw the rollout of the EzCater partnership and the initial wave of the 60 store closures. However, as the "value meal wars" intensified among competitors, the deep discounting required to maintain foot traffic further eroded the already thin margins.
September 18, 2026: The Filing
Recognizing that internal restructuring alone could not solve the liquidity crunch, the Board of Directors authorized the voluntary Chapter 11 filing to protect the long-term interests of stakeholders and ensure the continued operation of their most profitable locations.
Supporting Data: Analyzing the Margin Collapse
The financial data provided in the company’s recent CEO presentation paints a stark picture of the challenges facing multi-unit operators in 2026.
The EBITDA Deficit
The most alarming statistic is the 48% drop in store-level EBITDA. This decline was driven by a "perfect storm" of three factors:
- Beef Inflation: Protein costs reached record highs in 2026, significantly increasing the Cost of Goods Sold (COGS).
- Discounting Pressures: Under previous leadership, aggressive promotional pricing and "marketing misses" failed to generate the necessary volume to offset lower price points.
- Labor Overhead: Despite automation efforts, the cost of maintaining a full service-level staff remained high, particularly during the labor-intensive breakfast hours.
The Breakfast Pivot
The decision to alter the breakfast daypart in 120 locations is perhaps the most strategic data-driven move in the filing. While Wendy’s corporate has historically leaned heavily into breakfast as a growth engine, Meritage found that in certain markets, the labor and utility costs of staying open during early morning hours far outweighed the revenue generated. By opting out, Meritage realized an immediate EBITDA benefit of over $11 million.

New Revenue Streams: Catering
In a bid to diversify, Meritage launched a catering test with EzCater in March 2026. The data from this pilot was a rare bright spot:
- Full Rollout: Completed in May 2026 across 150 restaurants.
- Average Check Size: Approximately $500.
- Minimum Order: 10 people.
The catering model allows Meritage to utilize existing kitchen capacity during non-peak hours to fulfill high-margin, large-scale orders, providing a necessary buffer against declining individual foot traffic.
Official Responses: Leadership Weighs In
In a press release accompanying the filing, the Meritage Board of Directors emphasized that the move was a proactive strategy rather than a surrender.
"After more than a year of working constructively with its lenders and its franchisor toward a solution, the Company’s Board of Directors and management team determined that a voluntary, court-supervised restructuring is the most effective and proactive path to strengthen Meritage’s finances," the statement read.
The company further noted that the bankruptcy process would "address these headwinds directly and protect the long-term interests of its stakeholders, team members, guests, and communities."
Industry analysts suggest that the "constructive" relationship with the Wendy’s franchisor (Wendy’s Corporate) was essential. Wendy’s permission for Meritage to exit the breakfast daypart—despite the inevitable hit to comparable store sales (comps)—indicates that the franchisor is prioritizing the survival of its largest operators over top-line system-wide sales figures.
Implications: A Warning for the QSR Industry
The Meritage bankruptcy is not an isolated incident. It is the latest—and largest—in a string of franchisee failures that have defined 2026. This year has already seen bankruptcy filings from major operators of Hardee’s, Carl’s Jr., and Popeyes.

The Comparison to NPC International
Industry observers have drawn parallels between Meritage and the 2020 bankruptcy of NPC International. NPC, which operated nearly 400 Wendy’s units and 900 Pizza Huts, was undone by the unique pressures of the COVID-19 pandemic. However, the Meritage situation is arguably more concerning for the industry at large.
While NPC struggled with a sudden global shutdown, Meritage is struggling with the persistent economic fatigue of the mid-2020s. The current environment is defined by "sticky" inflation and a consumer base that has finally reached its limit regarding price increases. If a massive, well-capitalized operator like Meritage cannot maintain margins, it suggests that the traditional franchise model may need a fundamental overhaul.
The "Value Trap"
The Meritage filing highlights the "Value Trap" currently catching many QSR brands. To lure back consumers who are pulling back on spending, brands are forced into deep discounting. However, with the cost of labor and beef remaining high, these discounts are being subsidized almost entirely by the franchisee’s margins. Meritage’s 30-year low margin is a direct result of this unsustainable dynamic.
Looking Ahead
As Meritage moves through the Chapter 11 process, the industry will be watching closely to see if the company emerges as a leaner, more "catering-centric" entity. The successful restructuring of Meritage could provide a blueprint for other struggling mega-franchisees:
- Footprint Rationalization: Expect more operators to aggressively close "zombie" stores that are barely breaking even.
- Daypart Flexibility: The "Wendy’s Breakfast" experiment suggests that the era of mandatory 24/7 or 18-hour operations may be ending in favor of more localized, data-driven hours.
- Diversification: The shift toward B2B revenue (catering) will likely become a standard requirement for franchise profitability.
For now, the Meritage filing serves as a sobering reminder that in the 2026 restaurant landscape, scale is no longer a guaranteed shield against the harsh realities of a changing economy. The "Fresh, Never Frozen" brand now faces a frozen credit market and a heated battle for its very survival.