
 Dwi Wanna
The Great Drive-Thru Land Grab: 7 Brew Outmaneuvers Dutch Bros in $123.5 Million Bankruptcy Acquisition
The competitive landscape of the American drive-thru coffee industry has reached a fever pitch, as evidenced by a high-stakes bidding war within the bankruptcy courts. In a strategic move that signals an aggressive acceleration of its national footprint, the rapidly growing coffee franchise 7 Brew has successfully outbid its primary rival, Dutch Bros, to acquire the real estate assets and leases of dozens of Salad and Go locations.
The deal, valued at approximately $123.5 million, represents a significant pivot in the "coffee wars," as 7 Brew secures a foothold in high-traffic Sun Belt markets. This acquisition not only underscores the premium value of drive-thru-ready real estate but also highlights 7 Brew’s determination to challenge the market dominance of established players like Dutch Bros and Starbucks.
Main Facts: A Battle for Prime Real Estate
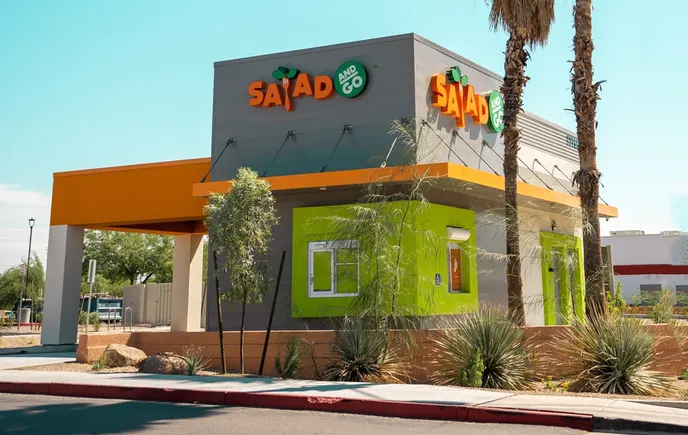
The transaction centers on the liquidation of assets belonging to the parent entities of the healthy fast-casual chain Salad and Go. In a bankruptcy proceeding that began with a seemingly secure private sale agreement between Dutch Bros and the debtors, 7 Brew intervened with a superior offer that disrupted the initial proceedings.
According to legal filings and statements from the law firm Reed Smith, which represented the interests involved, 7 Brew’s winning bid came in at roughly $18.5 million higher than the original $105 million offer put forward by Dutch Bros. While 7 Brew initially sought to acquire 73 sites for a total of $143 million, the finalized deal covers approximately 63 units.
The geographic distribution of these sites is concentrated in some of the most lucrative and fastest-growing regions in the United States:
- Arizona: 36 locations
- Texas: 19 locations
- Oklahoma: 5 locations
- Nevada: 3 locations
This acquisition allows 7 Brew to bypass the lengthy and often arduous process of site selection, permitting, and ground-up construction in these markets. By taking over existing leases and site assets formerly occupied by Salad and Go—a brand that, like 7 Brew, utilizes a small-footprint, drive-thru-only model—7 Brew can convert these locations into coffee stands with minimal structural overhaul.
Chronology of the Deal: From Private Agreement to Open Auction
The path to this acquisition was marked by legal tension and a breakdown of the initial private sale process. The timeline reveals a high-stakes game of corporate maneuvering:
- The Stalking Horse Bid: At the onset of the bankruptcy process, Dutch Bros established itself as the "stalking horse bidder." It reached a private sale agreement to purchase up to 65 Salad and Go units for $105 million. This agreement was intended to set a floor price for the assets.
- The 7 Brew Intervention: As the sale moved toward court approval, 7 Brew voiced formal objections. The company criticized the private nature of the agreement, arguing that it stifled competitive bidding and prevented the bankruptcy estate from achieving the maximum possible value for its creditors.
- The Revised Bid: 7 Brew backed its criticism with a tangible counter-offer. It initially proposed a $143 million deal for 73 sites. This forced the bankruptcy court to pivot from a private sale to a more transparent auction-style process.
- Negotiations and Lease Approvals: Over the following weeks, intensive negotiations took place involving landlords, the debtors, and the two coffee giants. During this phase, the total number of units in the 7 Brew package was refined. Ten sites were ultimately removed from the final 7 Brew deal—likely due to landlord objections, proximity to existing 7 Brew stands, or non-compete clauses involving other nearby coffee tenants.
- Final Approval: The court eventually approved 7 Brew as the winning bidder for the 63 sites, with Dutch Bros officially designated as the backup bidder should any part of the 7 Brew transaction fail to close.
Supporting Data: The Rapid Rise of 7 Brew
To understand the scale of this acquisition, one must look at the meteoric rise of 7 Brew. Founded in Rogers, Arkansas, in 2017, the brand has become one of the fastest-growing concepts in the Quick Service Restaurant (QSR) industry.
- Unit Growth: Earlier this year, 7 Brew celebrated a major milestone by surpassing 777 units. As of August 2024, the company reported having over 800 "stands" across 38 states.
- Target Milestones: The company is currently on a trajectory to reach 1,000 locations by 2026. This acquisition of 63 units in a single stroke provides a massive boost toward that goal, representing nearly 8% of the remaining distance to the 1,000-store mark.
- The Model: 7 Brew’s success is built on a "high-volume, small-footprint" model. Its stands typically do not offer indoor seating, focusing instead on double drive-thru lanes and "Texter" employees who take orders via tablets to speed up service. This model perfectly aligns with the real estate vacated by Salad and Go.
- Market Comparison: While 7 Brew is expanding rapidly, it still trails Dutch Bros, which operates over 900 locations and is a publicly traded company (NYSE: BROS). However, by outbidding Dutch Bros in this instance, 7 Brew has signaled that it has the capital and the institutional backing (including investment from Blackstone-backed companies) to compete for the best real estate in the country.
Official Responses and Legal Context
The legal team at Reed Smith, representing the interests of the transaction, highlighted the competitive nature of the bankruptcy auction. Legal experts noted that the intervention by 7 Brew was a "textbook example" of how competitive bidding can benefit a bankruptcy estate, ultimately yielding $18.5 million more for creditors than the initial private deal would have.
In court filings, 7 Brew’s representatives emphasized that their interest was not merely opportunistic but a core component of their national expansion strategy. "The opportunity to acquire a cluster of sites that are already optimized for a drive-thru-only model is rare," noted one industry analyst. "7 Brew recognized that losing these sites to Dutch Bros would not just be a missed opportunity for growth, but a strategic blow in key markets like Phoenix and Dallas."
Dutch Bros, while relegated to the backup bidder position, has remained focused on its own disciplined growth. In previous earnings calls, Dutch Bros leadership has emphasized "quality over quantity" in site selection, suggesting that while they were interested in the Salad and Go package, they were unwilling to match the premium price 7 Brew was prepared to pay to keep the sites out of a competitor’s hands.
Strategic Implications: The Future of the Drive-Thru
This acquisition has far-reaching implications for the coffee industry and the broader QSR real estate market.
1. The Real Estate "Arms Race"
The fact that 7 Brew paid a significant premium—approximately $1.96 million per site just for the leasehold interest and assets—shows how desperate the "arms race" for drive-thru real estate has become. With the rise of third-party delivery and a post-pandemic shift in consumer behavior, the "third place" (indoor seating) is becoming less valuable than the "drive-thru lane." Brands are now willing to pay "banker prices" for locations that offer high visibility and ease of access.
2. Sun Belt Dominance
By securing 36 sites in Arizona and 19 in Texas, 7 Brew is doubling down on the Sun Belt. These regions are experiencing the highest population growth in the U.S., coupled with a car-centric culture that is tailor-made for drive-thru coffee. This move puts 7 Brew in direct, block-by-block competition with Dutch Bros in its own backyard.
3. The Conversion Advantage
Converting an existing drive-thru site is significantly faster than building a new one. In a high-inflation environment where construction costs and interest rates remain elevated, the ability to "plug and play" into an existing Salad and Go shell provides 7 Brew with a speed-to-market advantage that could see these 63 stores opening much sooner than their competitors’ new builds.
4. Market Saturation and Landlord Power
The removal of 10 sites from the original 73-unit bid highlights the power of landlords and the risks of market saturation. As coffee stands proliferate, landlords are increasingly wary of "cannibalization"—where too many similar businesses in one shopping center or corridor hurt each other’s sales. The fact that some landlords rejected 7 Brew suggests that the "coffee bubble" may be nearing its limit in certain sub-markets.
Conclusion
The acquisition of the Salad and Go sites by 7 Brew is a landmark moment in the brand’s history. It represents a shift from organic, one-by-one growth to a bold, aggressive consolidation strategy. By outmuscling Dutch Bros in the bankruptcy courts, 7 Brew has proven it is no longer just a regional player from Arkansas, but a national contender with the financial muscle to dictate the terms of the industry’s expansion.
As these 63 locations transition from selling salads to serving "Breves" and "Energy" drinks, the industry will be watching closely. The success of this conversion will likely determine whether other brands follow suit, looking to bankruptcy courts and asset liquidations as the new frontier for rapid geographic expansion. For now, 7 Brew has secured a major victory, moving one giant step closer to its 1,000-store goal and reshaping the drive-thru landscape of the American Southwest.