
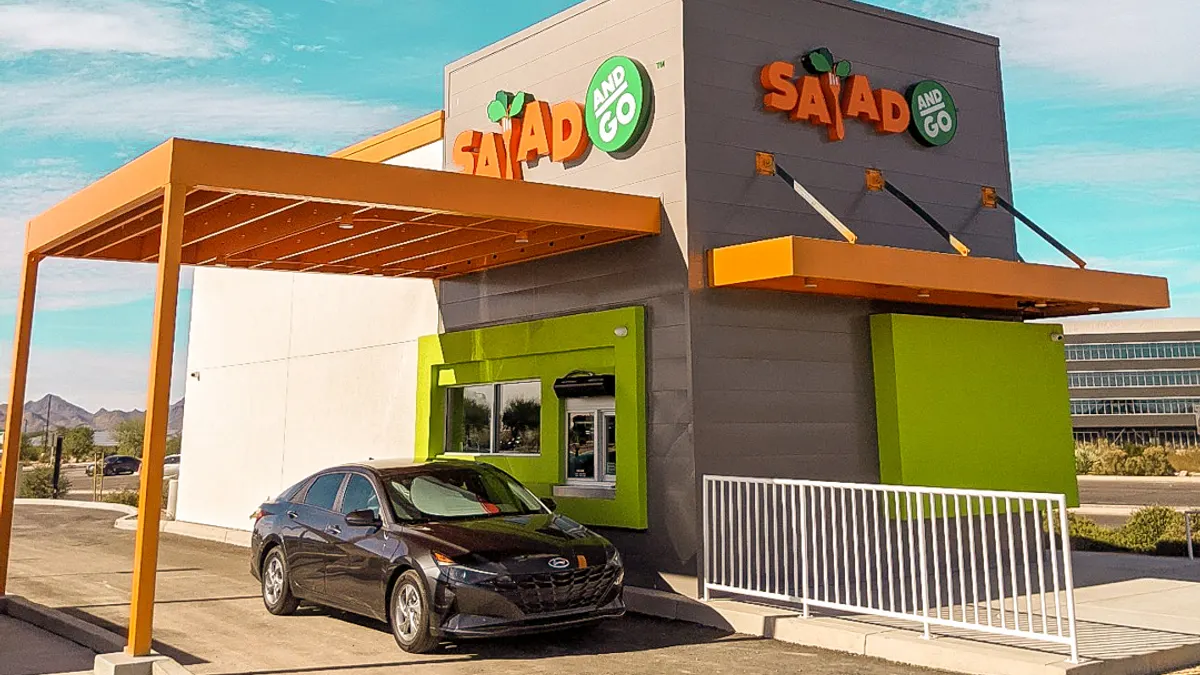
PHOENIX, AZ — The fast-casual landscape is witnessing a dramatic resurrection as Salad and Go, the Arizona-born drive-thru concept that revolutionized affordable healthy eating, prepares for a second act. Following a turbulent period of financial distress that culminated in a Chapter 11 bankruptcy filing earlier this year, the brand’s intellectual property and a significant portion of its assets have been acquired by Hospitality First Concepts.
The deal, approved by a federal bankruptcy court, marks a pivotal turning point for the chain. While approximately 100 former locations were liquidated or transitioned during the proceedings, the new ownership group, led by industry veterans and original stakeholders, has announced an aggressive plan to reopen core locations and pivot toward a national franchising model.
Main Facts: The Terms of the Resurrection
The acquisition by Hospitality First Concepts represents more than a mere real estate transaction; it is a strategic salvage of a brand that once held a unique "value-first" niche in the health food market. The group, spearheaded by Rodney Myers and supported by original investor Tom (last name withheld in initial filings) and operational lead Daniel, has secured the rights to the Salad and Go name, recipes, and operational blueprints.
Key elements of the transition include:
- Initial Focus on Arizona: The new owners intend to reopen several high-performing Arizona locations "as quickly as possible." These will serve as the flagship corporate stores to test the refined operational model.
- Shift to Franchising: In a departure from the previous corporate-heavy growth strategy, Hospitality First Concepts plans to introduce a nationwide franchising program, allowing the brand to scale without the massive capital expenditures that contributed to its previous downfall.
- Asset Liquidation: While the intellectual property (IP) was saved, nearly 100 former units were approved for sale to various bidders during the bankruptcy process to satisfy creditors.
Chronology: From Rapid Expansion to Chapter 11
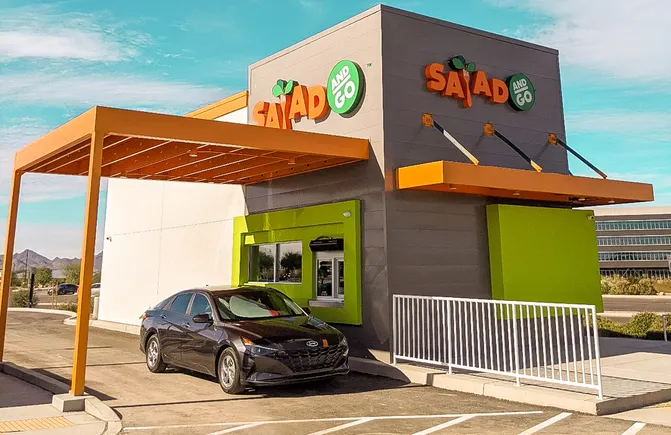
To understand the weight of the current acquisition, one must look at the meteoric rise and subsequent stumble of the brand. Founded with the mission to make fresh, organic food as affordable and convenient as traditional fast food, Salad and Go initially found immense success in the Southwest.
The Growth Phase (2020–2024):
Amidst a global shift toward health consciousness, Salad and Go expanded rapidly. By 2023, the chain had moved beyond its Arizona roots into Texas and Oklahoma. Investors were drawn to its "central kitchen" model, which was designed to lower costs by prepping produce in a single massive facility before distributing it to small-footprint drive-thrus.
The Onset of Friction (Late 2024–2025):
As inflation began to squeeze the restaurant industry, the brand’s commitment to low price points (often under $7 for a large salad) became a liability. Rising labor costs and the logistical nightmare of transporting fresh produce from a central Texas kitchen to distant markets began to erode margins.
The Tattersfield Era (2025–Early 2026):
In an attempt to stabilize the ship, the board hired Michael Tattersfield, the former CEO of Krispy Kreme, known for his turnaround expertise. Tattersfield initiated a "surgical" restructuring: closing underperforming units, reducing corporate overhead, and renegotiating vendor contracts. Most significantly, he shuttered the expensive central kitchen in Texas, moving toward a more localized supply chain. However, the debt load proved too heavy to overcome through operational tweaks alone.
The Bankruptcy (August 2026):
Facing a liquidity crisis and waning consumer demand in saturated markets, Salad and Go filed for Chapter 11 bankruptcy in early August. The filing was intended to allow the company to reorganize, but it ultimately led to the sale of the brand’s IP to Hospitality First Concepts in October 2026.
Supporting Data: The Financial Pressures of "Healthy" Fast Food
The failure of Salad and Go’s original corporate structure highlights the razor-thin margins inherent in the "value-health" segment. Unlike premium competitors like Sweetgreen, where salads can cost between $15 and $20, Salad and Go attempted to maintain a price floor that competed with McDonald’s and Taco Bell.
Data from the bankruptcy filings revealed several critical pressure points:

- Supply Chain Overextension: The central kitchen in Texas, while efficient at scale, required a high volume of sales to remain viable. When demand dipped in late 2025, the facility became a "white elephant," costing millions in monthly maintenance and logistics.
- Labor Inflation: In Arizona and Texas, the cost of entry-level labor rose by an average of 12% year-over-year. For a brand predicated on low prices, passing these costs to consumers was seen as a risk to the brand’s core identity.
- Real Estate Debt: The rapid acquisition of drive-thru sites at the height of the real estate market left the company with high lease obligations that could not be sustained by lower-than-projected unit volumes.
Despite these hurdles, the broader "salad" segment remains a darling for investors. For instance, the health-focused chain Crisp & Green recently acquired 33 units from the Salad Collective (the parent of Mad Greens and Snappy Salad), signaling that there is still significant appetite for consolidation and growth in the sector.
Official Responses: Rebuilding with "Infectious Passion"
The new leadership team is leaning heavily on the brand’s original DNA while promising a more disciplined fiscal approach. Rodney Myers, the face of the new ownership group, expressed a mixture of nostalgia and strategic optimism in a recent public statement.
"When I saw the opportunity to rebuild Salad and Go, I couldn’t pass it up," Myers stated via social media. "Tom has been my longtime partner and was an original investor in Salad and Go. And Daniel’s passion for what he does is infectious. Bringing the three of us together to rebuild this brand just made sense."
Myers emphasized that the "reboot" would focus on the basics: high-quality ingredients, speed of service, and a sustainable price point that doesn’t sacrifice the company’s solvency. The decision to keep the first wave of reopened stores as company-owned entities in Arizona is intended to "perfect the prototype" before inviting franchisees into the fold.
Industry analysts suggest that the return of original investors like "Tom" is a calculated move to restore confidence among the loyal "cult" following the brand enjoyed in its early years.
Implications: The Future of the Drive-Thru Salad
The rebirth of Salad and Go under Hospitality First Concepts carries several major implications for the restaurant industry at large.

1. The Death of the "Mega-Central Kitchen" for Startups:
The Salad and Go saga serves as a cautionary tale for the centralized production model. While it works for giants like Starbucks, smaller chains may find that localized prep and regional supply chains offer the flexibility needed to survive economic volatility.
2. The Franchising Pivot:
By moving to a franchising model, the new Salad and Go will shift the capital risk of store construction and local labor management to third-party operators. This allows the brand to grow its footprint and "mindshare" rapidly while the parent company focuses on brand marketing, menu innovation, and supply chain logistics.
3. The Persistence of "Value Health":
The fact that a buyer emerged so quickly for Salad and Go’s IP suggests that the market still believes in the "affordable healthy" thesis. Consumers are increasingly weary of the "luxury salad" trend. If Myers and his team can find the "Goldilocks zone"—pricing that is higher than the original $7 but significantly lower than $18—they may capture a massive, underserved demographic of middle-class commuters.
4. A Resurgence of Legacy Brands:
Salad and Go isn’t the only brand seeing a revival. The recent slow return of Souplantation and Sweet Tomatoes (which filed for Chapter 7 in 2020) indicates a "nostalgia cycle" in the food industry. Investors are finding it more cost-effective to buy and fix a broken brand with existing name recognition than to build a new one from scratch.
Conclusion
As the first of the Arizona locations prepare to flip their "Open" signs back on, the industry will be watching closely. The failure of Salad and Go 1.0 was a result of aggressive over-scaling and a rigid operational model. Salad and Go 2.0, under Hospitality First Concepts, appears to be a leaner, more strategically flexible entity.
Whether the brand can maintain its "low-price" soul while adopting a "high-growth" franchise body remains the $100 million question. For the residents of Arizona, however, the immediate victory is the return of their favorite drive-thru cobb salads and lemonades—a small sign that even in a volatile economy, good ideas often get a second chance.