
DUBLIN, Ohio — Facing a challenging fiscal landscape defined by declining foot traffic and internal franchisee instability, The Wendy’s Company has officially launched a multi-year strategic overhaul dubbed "Dave’s Way." The plan, detailed during the company’s third-quarter 2026 earnings call on Thursday, represents a fundamental shift in how the world’s third-largest burger chain intends to compete in an increasingly saturated and price-sensitive quick-service restaurant (QSR) market.
The announcement comes at a pivotal moment for the brand. Alongside the unveiling of the strategy, Wendy’s leadership confirmed the unanimous rejection of a $1.4 billion unsolicited takeover bid from Trian Fund Management and reported a significant 5.7% drop in U.S. comparable sales for the third quarter. Led by newly appointed CEO Robert Wright, "Dave’s Way" seeks to return the brand to its foundational principles of food quality and operational excellence while modernizing its digital and delivery infrastructure.
I. Main Facts: The Five Pillars of "Dave’s Way"
The "Dave’s Way" initiative is not merely a marketing slogan but a structured operational framework designed to stabilize the brand’s trajectory through 2027. CEO Robert Wright outlined five core pillars intended to restore Wendy’s market share and improve restaurant-level profitability:
- Food Quality and Value Innovation: A total menu refresh focused on "distinctive, fresh, and craveable" items, including the removal of low-margin, high-complexity products.
- Brand and Marketing Evolution: A shift in creative direction, supported by a new agency and a data-driven approach to media spending to drive immediate customer visits.
- Operational Excellence: Re-establishing rigorous brand standards and implementing a metric-driven performance system to bridge the gap between high- and low-performing units.
- Digital and Delivery Acceleration: Closing the "delivery gap" compared to industry peers and enhancing the seamlessness of the mobile app and loyalty experience.
- Portfolio Optimization: Direct intervention in franchisee health, including the strategic acquisition and refranchising of underperforming locations.
Perhaps the most significant immediate change is the company’s decision to make the breakfast daypart optional for franchisees. This move allows operators to reallocate labor and resources to more profitable lunch and dinner windows, a decision Wendy’s estimates could add up to $200 million in restaurant-level EBITDA across the system.
II. Chronology: The Path to the Turnaround
The road to "Dave’s Way" began in early 2026 as Wendy’s grappled with a post-inflationary cooling of consumer spending.
- Early 2026: Leadership Transition. Following several quarters of stagnant growth, Wendy’s appointed Robert Wright as CEO. Wright, a veteran of the QSR industry, was tasked with auditing the brand’s operations and identifying why Wendy’s was losing ground to competitors like McDonald’s and specialized burger chains.
- Mid-2026: Franchisee Disturbance. Financial pressures began to mount within the franchise network. Meritage Hospitality Group, one of the brand’s largest operators, faced significant headwinds, eventually leading to a bankruptcy filing in September. This served as a catalyst for Wendy’s to accelerate its portfolio optimization plans.
- August 2026: Marketing Shake-up. Wendy’s hired Tariq Hassan, formerly of McDonald’s, as Chief Marketing and Customer Growth Officer. This was followed by the termination of long-standing agency relationships in favor of a new creative partner.
- September 2026: The "Soft Launch." Before going public, Wendy’s presented the "Dave’s Way" strategy to global franchisees and suppliers at a private convention. The company reported a "substantial increase" in operator optimism following this meeting.
- November 2026: The Public Unveiling. The Q3 earnings release served as the formal debut of the strategy, punctuated by the high-profile rejection of the Trian Fund Management acquisition offer.
III. Supporting Data: The Numbers Behind the Strategy
The urgency of the "Dave’s Way" plan is underscored by several critical data points revealed in the Q3 2026 earnings report and subsequent commentary:
The Performance Gap
Wendy’s internal data highlights a stark disparity between its top-performing and bottom-performing restaurants. Wright noted that stores in the top quintile for customer satisfaction outperform those in the bottom quintile by over 500 basis points in traffic. Furthermore, the fastest drive-thrus are nearly two minutes quicker than the slowest, a metric that directly correlates with repeat business and total daily volume.
The Breakfast Calculation
Since launching breakfast nationally in 2020, Wendy’s has struggled to achieve consistent profitability in the morning hours across all markets. By making the daypart optional, the company believes it can recover lost morning sales through improved efficiency during peak hours. Early tests showed that restaurants removing breakfast saw immediate gains in lunch and dinner profitability due to more focused labor deployment.
Delivery and Digital Growth
Wendy’s currently lags behind its primary competitors in delivery penetration. However, recent tests involving aggressive marketplace promotions and improved digital visibility resulted in sales lifts of 10% to 20% in delivery. As of November 2026, over 90% of U.S. franchise restaurants have opted into these new delivery promotions, up from less than 50% just months prior.
Portfolio Stabilization
The financial health of the system is a primary concern. Wendy’s has signed a letter of intent to acquire up to 163 restaurants from the bankrupt Meritage Hospitality Group. This move is part of a broader "disciplined approach" to ensure that vital locations do not go dark. In a related transaction, 42 units were sold to Divine Infinity Operations for more than $18 million, demonstrating a market for Wendy’s assets even amidst corporate restructuring.
IV. Official Responses: Leadership and Board Perspectives
The earnings call was marked by a tone of resolute independence. The rejection of the $1.4 billion bid from Trian Fund Management—a group led by activist investor Nelson Peltz, who has long been involved with Wendy’s—served as a vote of confidence in the current management team.
Robert Wright, CEO:
"Dave’s Way is our multi-year strategy designed to put our strengths and values back at the center of how we compete. We’re confident that we have the right strategy, execution, and resources to restore Wendy’s to its full potential and drive meaningful shareholder value. It’s also the standard for how we operate, make decisions, and hold ourselves accountable."
The Independent Committee of Directors:
In a statement regarding the Trian bid, the committee noted they "unanimously rejected" the unsolicited offer, concluding that the company’s standalone plan under Wright’s leadership offered superior value to shareholders than a private buyout at the proposed price.
Regarding Menu Innovation:
Wright emphasized that the brand would no longer chase "complexity for complexity’s sake." He stated, "We’ll be disciplined in what we scale, moving forward with the innovations that resonate with customers, work best operationally, and drive sales and profits to our restaurants."
V. Implications: What "Dave’s Way" Means for the Future
The success of "Dave’s Way" will be a litmus test for whether a legacy QSR brand can pivot its operations without losing its core identity. Several long-term implications emerge from this strategy:
1. The End of the "One-Size-Fits-All" Model
By allowing franchisees to opt out of breakfast, Wendy’s is acknowledging that local market dynamics often trump corporate mandates. This flexibility could improve the financial health of struggling operators but may also lead to customer confusion regarding store hours and menu availability. The brand will need to rely heavily on its digital app to communicate these variations to consumers.
2. A 2027 Horizon for Brand Renewal
Wendy’s has set 2027 as the target for a "fully refreshed menu experience." This suggests that the next 12 to 18 months will be a period of intense experimentation. Customers can expect to see higher-quality ingredients—such as the "thicker, crispier bacon" and "richer, creamier Frostys" currently in testing—but may also see the disappearance of niche menu items that slow down kitchen throughput.
3. Corporate as a Safety Net
The decision to acquire 163 Meritage-owned stores signals that Wendy’s corporate is willing to use its balance sheet to protect the brand’s physical footprint. While the ultimate goal is to refranchise these units to "stronger hands," the interim period will require Wendy’s to prove it can run these stores more efficiently than the previous owners.
4. The Value War Escalation
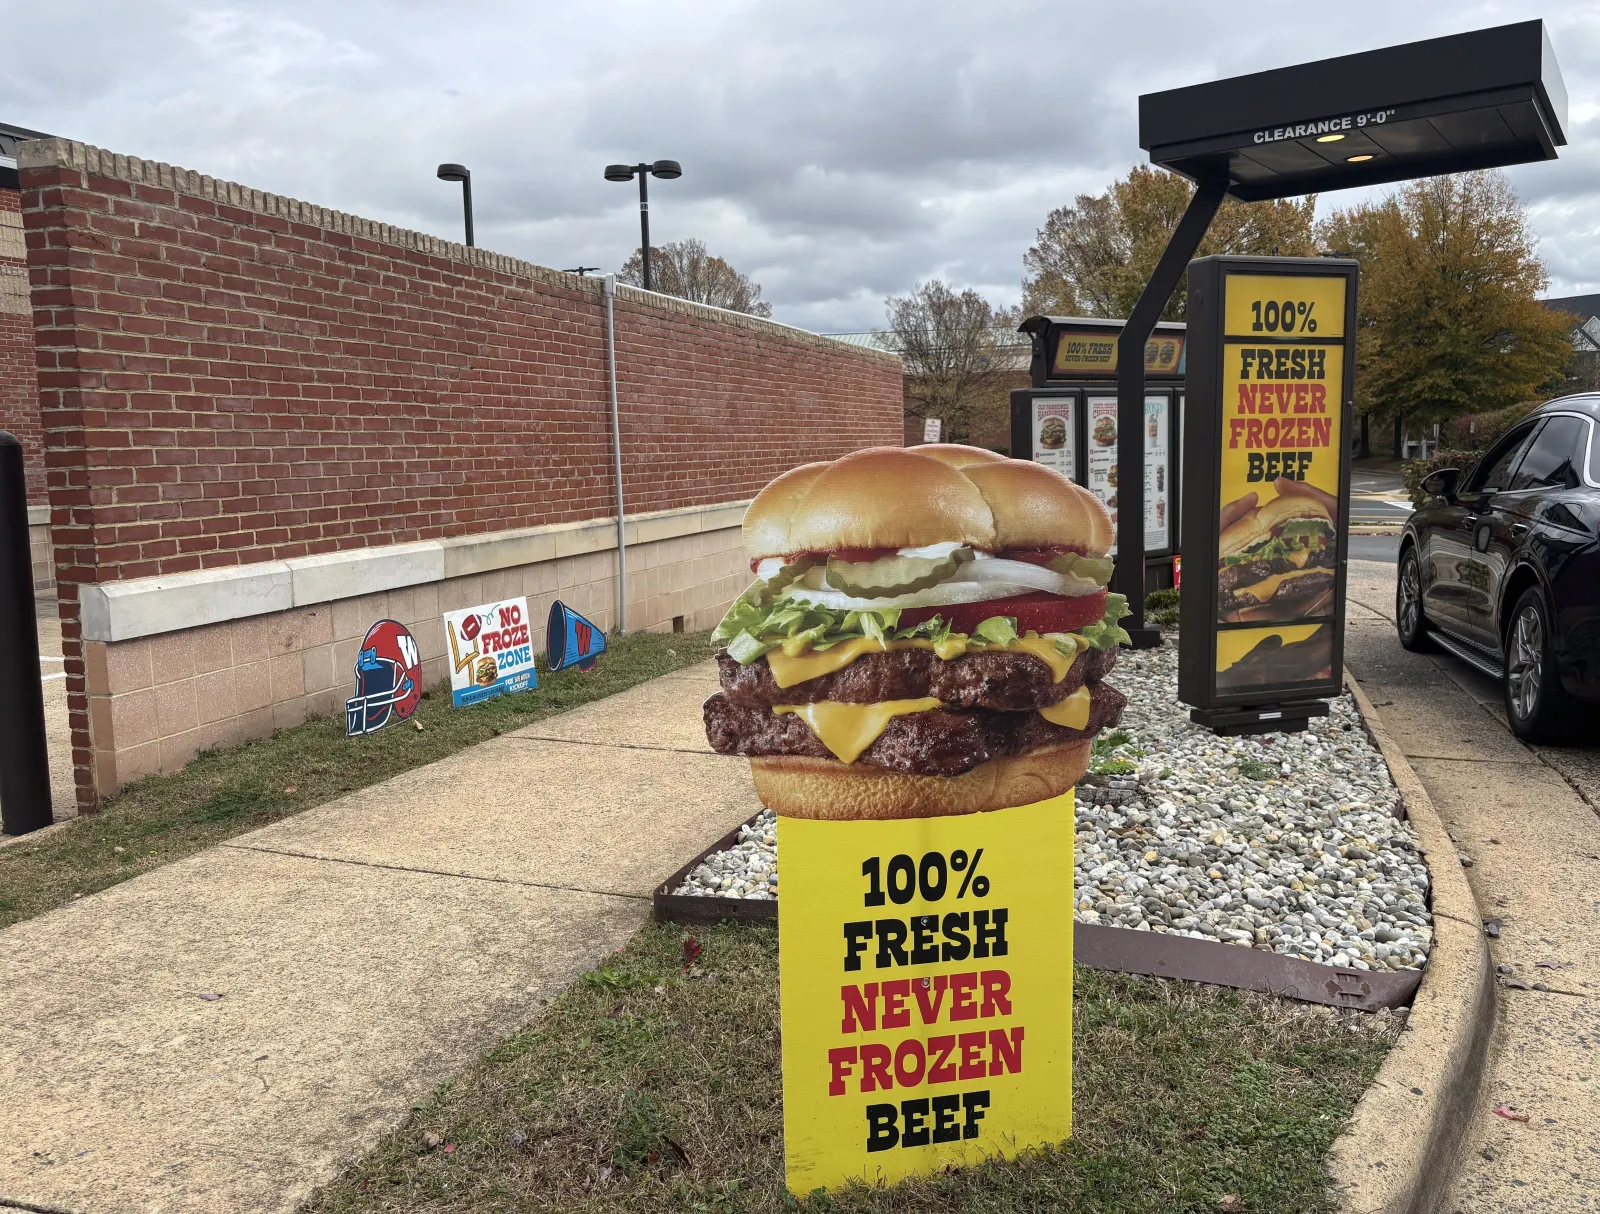
The $7.99 Dave’s Single Combo promotion is a direct shot across the bow of competitors who have been aggressive with $5 meal deals. Wendy’s is betting that consumers are willing to pay a slight premium for "fresh, never frozen" beef if the value proposition is clearly communicated. The success of this pricing strategy will determine if Wendy’s can maintain its "premium-fast" positioning or if it will be forced into a race to the bottom on price.
5. Digital Transformation as a Necessity
With delivery and digital ordering becoming the primary growth engines for the industry, Wendy’s "ecosystem" approach—integrating the app, website, and third-party aggregators—is no longer optional. The company’s ability to use "personalization and relevant offers" to drive frequency will be the key metric for investors to watch in 2027.
As Wendy’s moves forward with "Dave’s Way," the ghost of founder Dave Thomas looms large. The strategy is a gamble that by looking backward at Thomas’s original focus on quality and simplicity, the company can find its way forward in a digital-first, hyper-competitive future. For now, the board’s rejection of the Trian bid has bought Wright and his team the time they need to prove that Dave’s Way is indeed the right way.