
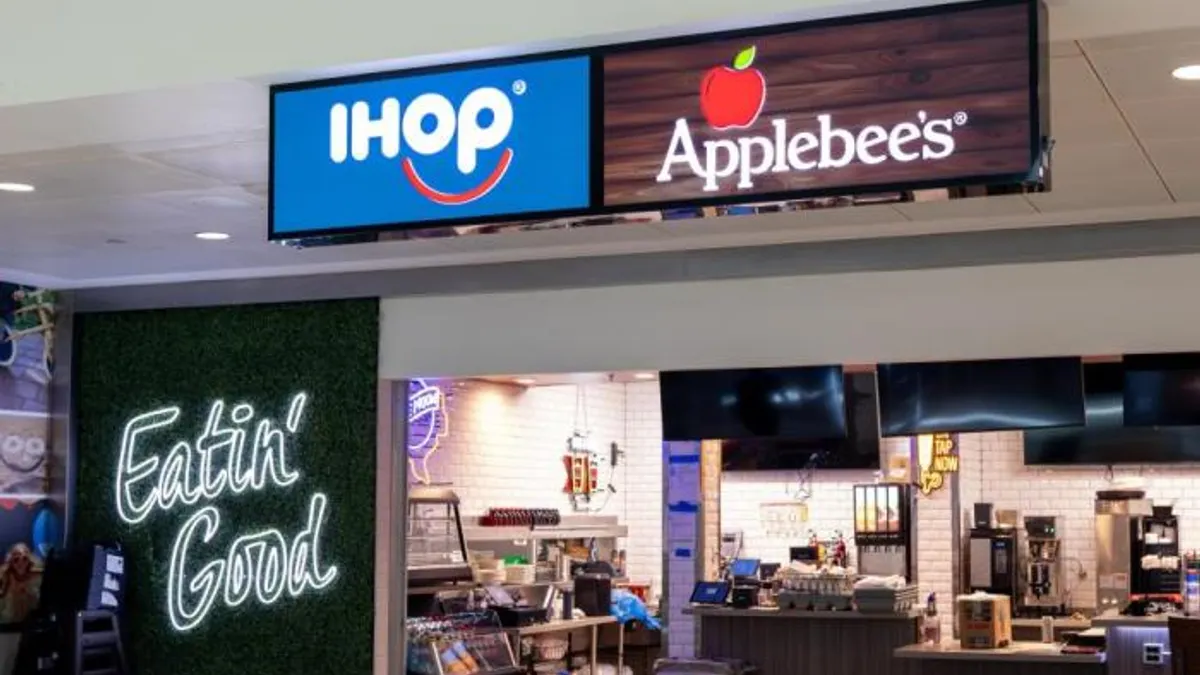
GLENDALE, CA — In a decisive move to protect its corporate autonomy and long-term strategic roadmap, Dine Brands Global, Inc.—the parent company of iconic American restaurant chains Applebee’s Neighborhood Grill + Bar and IHOP—has officially adopted a limited-duration stockholder rights plan. The maneuver, commonly referred to in high-stakes corporate finance as a "poison pill," comes in direct response to reports of a coordinated buyout attempt by a group of activist investors seeking to take the company private.
The announcement, made public on October 30, 2026, signals a burgeoning conflict between the board of Dine Brands and a consortium of investors led by Arkhouse Management and Cobblers Cove Capital. As the casual dining sector faces a wave of consolidation and privatization, Dine Brands’ refusal to entertain an immediate sale highlights a widening rift between market speculators seeking short-term premiums and corporate leadership focused on multi-year brand transformations.
I. Main Facts: The Architecture of the Defense
The stockholder rights plan adopted by the Dine Brands Board of Directors is a classic defensive mechanism designed to prevent any single entity from gaining a controlling interest without paying a fair premium to all shareholders. Under the terms of the plan, the company will issue one right for each share of common stock held by stockholders of record as of the close of business on November 9, 2026.
The Thresholds and Penalties
The plan is structured with specific triggers intended to dilute the holdings of any aggressive acquirer:
- Activist Threshold: The rights become exercisable if an individual or group acquires "beneficial ownership" of 10% or more of Dine Brands’ outstanding common stock.
- Passive Investor Threshold: For institutional or passive investors who do not seek to influence control, the threshold is set higher at 20%.
- The "Flip-In" Provision: Should a party cross these thresholds, all other stockholders will be entitled to purchase additional shares of Dine Brands stock at a 50% discount. This massive dilution effectively makes a hostile takeover prohibitively expensive for the acquirer.
The plan is scheduled to remain in effect until October 27, 2027, providing the board with a twelve-month "breathing room" period to execute its current business strategy and evaluate any formal offers that may arise.
The Impetus: A $39 Per Share Bid
The defensive move follows a flurry of market activity triggered by a Bloomberg report on October 28, 2026. According to sources familiar with the matter, Arkhouse Management and Cobblers Cove Capital have been quietly building a position in Dine Brands. The group has reportedly gained "economic exposure" to nearly 20% of the company’s shares through a combination of direct holdings and complex financial instruments, such as total return swaps.
The rumored bid price is $39.00 per share—a significant premium over the $32.01 closing price recorded on October 27, the day before the takeover interest became public.
II. Chronology: The Week That Shook Glendale
The escalation from a standard trading week to a full-blown corporate defense took place over a period of just four days, illustrating the speed at which activist investors can move in the current high-inflation, low-valuation environment.
- October 27, 2026: Dine Brands (NYSE: DIN) trades at a steady $32.01. Market sentiment is cautious but stable, as the company continues to rollout its dual-branded IHOP/Applebee’s locations.
- October 28, 2026: Bloomberg breaks the news that Arkhouse Management and Cobblers Cove Capital are mulling a takeover bid. The report suggests the investors believe the company is undervalued and would perform better away from the quarterly scrutiny of public markets. Trading volume spikes, and the share price begins to climb toward the rumored $39 mark.
- October 29, 2026: Dine Brands’ board meets in an emergency session to review the reports and assess the company’s vulnerability. They determine that the "economic exposure" of the activist group (near 20%) poses a threat to the board’s ability to negotiate on behalf of all shareholders.
- October 30, 2026: Dine Brands issues a formal press release announcing the adoption of the stockholder rights plan. CEO John Peyton issues a statement reaffirming the board’s confidence in the company’s independent future.
III. Supporting Data: Financial Health and Market Context
To understand why Dine Brands has become a target for activists, one must look at the broader financial landscape of the casual dining industry in 2026.
Stock Performance and Valuation
Before the takeover rumors, Dine Brands’ stock had faced headwinds common to the "sit-down" restaurant segment. Rising labor costs and fluctuating commodity prices have pressured margins across the industry. However, Dine Brands has maintained a relatively healthy balance sheet, bolstered by its "asset-light" franchise model. By franchising the vast majority of its Applebee’s and IHOP locations, the parent company generates steady royalty income without the overhead of operating thousands of individual restaurants.
The Dual-Branding Catalyst
A key piece of data in Dine Brands’ defense is the success of its dual-branded concept. In January 2026, the company opened a landmark IHOP-Applebee’s hybrid at Dallas Love Field Airport. This model allows the two brands to share a kitchen, reducing back-of-house costs while maximizing daypart coverage (IHOP dominating breakfast/brunch and Applebee’s leading lunch/dinner/late-night).
Early data from the Dallas location and subsequent international prototypes suggested a potential 20% to 30% increase in unit-level productivity compared to standalone stores. Management argues that the full value of this "dual-brand" rollout has not yet been "baked into" the current stock price, making the $39 bid an "opportunistic" attempt to buy the company before the strategy fully matures.

IV. Official Responses: Leadership Stands Firm
The rhetoric from Dine Brands’ executive suite has been one of calculated defiance. In an emailed statement, CEO John Peyton emphasized that the poison pill is not a refusal to talk, but a tool to ensure fairness.
"This plan is a standard practice to ensure all stockholders are protected from opportunistic share accumulations that could lead to an effective control position without stockholders receiving an appropriate premium value," Peyton stated. He further noted that the board remains "executing against a strategy to unlock our brands’ full potential by investing in long-term initiatives that are driving results."
The Activist Perspective
While Arkhouse Management and Cobblers Cove Capital have not issued an official counter-statement, the logic of their "economic exposure" is clear. Activist investors often argue that public companies like Dine Brands are weighed down by the "public company discount"—the costs associated with regulatory compliance and the pressure to meet short-term quarterly earnings targets. By taking the company private, the investors likely believe they could accelerate store closures of underperforming locations and more aggressively pivot toward the dual-branded model without the glare of public disclosures.
V. Implications: A Changing Landscape for Casual Dining
The battle for Dine Brands is not an isolated incident; it is part of a systemic shift in the restaurant industry. As the article notes, Dine Brands is following a path trodden by other major players in the fast-food and casual dining space.
The "Going Private" Trend
- Pizza Hut: Under Yum! Brands, Pizza Hut has undergone significant structural changes, with various international arms and major franchisees moving toward private ownership to facilitate long-term digital transformations.
- Wendy’s: Earlier in the same week as the Dine Brands news, Wendy’s received a $1.4 billion bid to go private. Unlike Dine Brands, Wendy’s has not yet adopted a poison pill, leading to speculation that their board may be more amenable to a deal.
- Jack in the Box: In 2025, the burger chain adopted a similar stockholder rights plan to fend off Sardar Biglari, a well-known activist investor who has famously sparred with the boards of Cracker Barrel and other restaurant chains.
Why Casual Dining is Under Fire
Casual dining occupies a precarious middle ground in 2026. It lacks the convenience of Quick Service Restaurants (QSR) like McDonald’s and the "experience" premium of fine dining. To survive, brands like Applebee’s and IHOP have had to innovate through technology (handheld server tablets, AI-driven loyalty programs) and creative real estate (airports, "ghost kitchens," and dual-branding).
Activists see these "legacy" brands as "cash cows" that can be milked for profit if managed with a more ruthless focus on efficiency. Conversely, corporate boards view these brands as cultural institutions that require careful, long-term stewardship to maintain "share of stomach" in a crowded market.

What Lies Ahead for Dine Brands?
The adoption of the poison pill does not mean a sale is impossible. Instead, it shifts the leverage back to the Board of Directors. If Arkhouse and Cobblers Cove truly want the company, they will likely have to increase their bid significantly above $39 to convince the board that a sale provides more value than the current independent strategy.
If the activists persist, the industry could see a "proxy battle," where the investors attempt to nominate their own slate of directors to the board during the 2027 annual meeting. For now, however, the "poison pill" has successfully frozen the board’s opponents in their tracks.
Conclusion
As the October 27, 2027 expiration date for the rights plan looms in the distance, all eyes will be on Dine Brands’ quarterly performance. If John Peyton and his team can prove that the dual-branded IHOP/Applebee’s locations are the future of American dining, the stock may naturally rise above the $39 bid, rendering the activist threat moot. However, if growth stalls, the "pill" may only have delayed the inevitable privatization of two of America’s most recognizable restaurant marques.
For the employees at the Dallas Love Field airport location—and the thousands of other IHOPs and Applebee’s across the globe—the corporate maneuvering in Glendale may seem distant. Yet, the outcome of this financial chess match will ultimately determine the menu, the technology, and the very atmosphere of the "neighborhood" grill for years to come.