
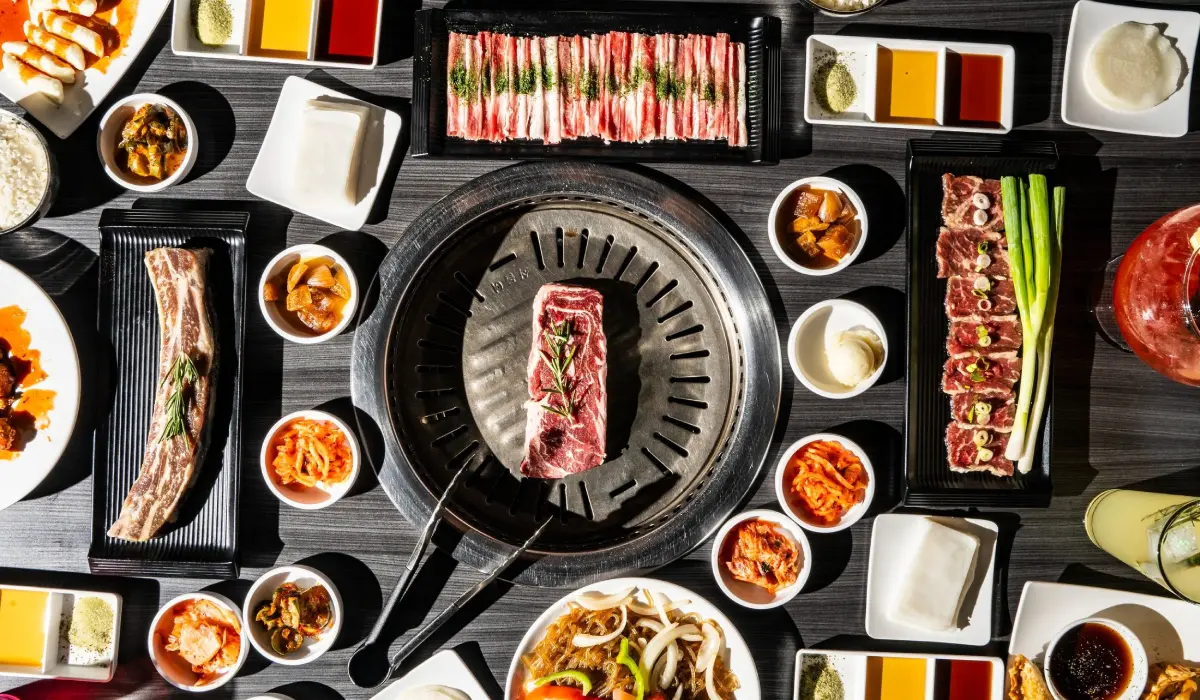
In a move that signals a seismic shift in its corporate identity, GEN Korean BBQ is effectively dismantling its identity as a traditional restaurant chain to emerge as a Consumer Packaged Goods (CPG) powerhouse. The company, once characterized by its ambitious national expansion of high-energy, all-you-can-eat dining rooms, is now aggressively pivoting toward the retail sector. This transformation involves a $100 million divestiture of nearly its entire restaurant portfolio and a brutal 75 percent reduction in corporate overhead.
The restructuring marks one of the most dramatic "asset-light" pivots in the modern American casual dining landscape. By offloading the operational complexities of brick-and-mortar locations, GEN aims to capitalize on the soaring demand for Korean flavors in American households, trading the volatility of the hospitality industry for the scalable margins of the grocery deli and freezer sections.
I. Main Facts: The $100 Million Exit and Corporate Downsizing
The centerpiece of GEN’s restructuring is a massive transaction with the Chubby Cattle Group. Under a binding letter of intent signed in October, GEN has agreed to sell 47 of its U.S. restaurant locations for a total consideration of up to $100 million. This deal is not merely a financial exit but a strategic hand-off; Chubby Cattle will assume the operational responsibilities and lease obligations for these sites, allowing GEN to shed the heavy weight of real estate and labor management.
The Lean Corporate Model
To align with its new mission, GEN is executing a "scorched-earth" policy regarding its internal infrastructure. Chairman and CEO David Kim announced that the company will reduce its corporate overhead by 75 percent. For years, GEN maintained a robust back-office staff designed to support the opening of 10 to 15 new restaurants annually. With that growth engine now shuttered, those roles have become redundant.
Layoffs are scheduled to begin in the fourth quarter of 2024. While the exact number of affected employees has not been disclosed, the cuts will be sweeping. Kim has made it clear that the "New GEN" will be a lean, specialized organization. Every remaining role must directly contribute to the growth of the CPG business or ensure regulatory and financial compliance as a public entity.
What Remains of the Restaurant Empire
Post-transaction, GEN will retain only one physical restaurant: its location in Cerritos, California. This site will serve as a "living laboratory"—a hub for research and development, product testing, and training. Additionally, the company will maintain its 49 percent stake in five Chubby Group restaurants through an existing joint venture, providing a residual link to the dining sector without the burden of primary operations.
II. Chronology: From Aggressive Expansion to Strategic Retreat
The path to this restructuring was paved by a sharp reversal in market conditions and internal performance.
- Early 2023 – Mid 2024: The Growth Phase. GEN entered 2024 with high-flying ambitions. The company had publicly set a target of reaching 75 company-owned restaurants by the end of 2026. At the time, the "all-you-can-eat" model seemed resilient to inflationary pressures.
- Q3 2024: The Reality Check. As the year progressed, the casual dining sector began to soften. GEN’s internal data showed weakening restaurant sales and mounting operating losses. Simultaneously, the company’s pilot program for frozen BBQ meats in grocery stores began to show significant promise, offering a higher return on invested capital than building new $3 million restaurants.
- October 2024: The Pivot Point. GEN signed the binding letter of intent with Chubby Cattle Group. This signaled to investors that the company was no longer prioritizing foot traffic, but rather shelf space.
- November 2024: The Earnings Call Revelation. During the Q3 earnings call, David Kim laid out the "New GEN" roadmap, confirming the 75 percent overhead reduction and the shift toward becoming a CPG-first enterprise.
- 2025–2027: The CPG Rollout. The company is now entering a multi-year phase of retail expansion, targeting a $40 million annualized revenue run rate for its CPG division by the end of 2027.
III. Supporting Data: The Financial Imperative
The decision to pivot was not merely a creative choice but a financial necessity. GEN’s Q3 2024 financial results highlighted a business under significant duress.
Declining Performance and Widening Losses
- Revenue: Declined 3.3 percent year-over-year, falling to $48.7 million from $50.4 million.
- Operating Loss: Widened significantly to $6 million, up from $3.7 million in the prior year.
- Net Loss: Increased to $5.5 million compared to $3.6 million in Q3 2023.
- Adjusted EBITDA: Reported a loss of $600,000, a three-fold increase from the $200,000 loss in the previous year.
The Debt Burden
The company’s balance sheet also showed signs of strain. Total outstanding debt reached $26.8 million by the end of September 2024, nearly doubling from the $14.6 million recorded at the end of 2023. With only $2.9 million in cash and cash equivalents on hand, the $100 million infusion from the Chubby Cattle deal is critical for debt retirement and funding the CPG transition.
The Retail Bright Spot
While the restaurants struggled, the retail footprint expanded. GEN is already present in major chains including:
- Albertsons, Safeway, and Vons
- Stater Bros. and Smart & Final
- Bristol Farms and Vallarta Supermarkets
- Select Costco regions
In Q3 alone, GEN added distribution in 55 Vallarta locations and 14 Bristol Farms stores. They also successfully breached non-traditional markets, including UCLA’s dining halls and SoFi Stadium, proving the brand’s versatility outside of its own four walls.
IV. Official Responses: Leadership’s Vision for "New GEN"
CEO David Kim has been transparent about the "right-sizing" of the company, framing it as a necessary evolution rather than a retreat.
“GEN today carries the corporate structure of a company that was opening 10 restaurants a year. The company we are becoming needs a fraction of that,” Kim stated during the Q3 call. His comments reflect a pragmatic approach to corporate survival in a high-interest-rate environment where labor and food costs continue to squeeze restaurant margins.
Kim also emphasized the efficiency of the CPG model. Unlike the restaurant business, which requires massive capital expenditure for construction and staffing, GEN’s retail products are manufactured through third-party partners in the U.S. and South Korea. “Every role in the new GEN must earn its place by growing CPG or keeping us compliant,” Kim reiterated.
Regarding future partnerships, Kim hinted at a major upcoming milestone: Walmart. While no definitive agreement has been signed, Kim noted that Walmart executives expressed interest ahead of their usual purchasing schedule, suggesting a potential 2027 rollout that could exponentially increase GEN’s volume.
V. Implications: A New Blueprint for Food Brands
The transformation of GEN Korean BBQ carries significant implications for the broader food and beverage industry.
1. The Rise of the "Asset-Light" Strategy
GEN’s move follows a growing trend where established restaurant brands seek to de-risk by becoming licensing or product companies. By removing the "roof and four walls," GEN eliminates the risks associated with local minimum wage hikes, utility increases, and fluctuating commercial real estate markets. If successful, GEN could serve as a blueprint for other ethnic dining chains that have strong brand equity but struggle with the operational overhead of the American service industry.
2. The Democratization of Korean Cuisine
For the consumer, this shift represents the continued "mainstreaming" of Korean BBQ. By moving from a $35-per-person "all-you-can-eat" experience to a $15 frozen or refrigerated meal at a local grocery store, GEN is making the cuisine accessible to a much wider demographic. The company’s plan to enter the "refrigerated ready-to-eat" category in 2027—targeting grocery delis with fully cooked meats—directly competes with the "home meal replacement" (HMR) trend that has dominated post-pandemic consumer habits.
3. Workforce Disruption
The human cost of this pivot is substantial. The 75 percent reduction in corporate overhead represents a significant loss of institutional knowledge and employment. Furthermore, while the 47 restaurants will continue to operate under Chubby Cattle, the change in ownership often leads to shifts in culture, management, and benefits for thousands of front-line workers.
4. High-Margin Diversification
GEN’s strategy to move into snacks, sauces, and beverages is a classic high-margin play. While meat products have high revenue but lower margins due to protein costs, "pantry staples" like BBQ sauces and Korean-inspired snacks offer much more attractive profitability profiles. This diversification is essential for GEN to achieve the "annualized CPG revenue run rate" it has promised investors.
5. Risk of Brand Dilution
The primary risk for GEN lies in brand equity. The "GEN" name was built on the smoke, sizzle, and social atmosphere of its restaurants. As those restaurants transition to new management and the brand becomes primarily associated with a plastic tray in a grocery aisle, there is a risk that the "premium" or "experiential" nature of the brand could be diluted. The Cerritos R&D location will bear the heavy burden of maintaining the brand’s culinary standards in a mass-produced format.
Conclusion
GEN Korean BBQ is betting its future on the American grocery cart. By liquidating its restaurant fleet and slashing its corporate footprint, the company is attempting a high-stakes pivot that prioritizes scalability and margin over physical presence. If the "New GEN" can successfully navigate the cutthroat world of retail distribution and maintain its flavor profile in a microwaveable format, it may emerge as a more profitable, albeit much smaller, version of its former self. However, the transition from hospitality to manufacturing is fraught with logistical challenges, and the industry will be watching closely to see if a brand born in the dining room can truly survive—and thrive—on the supermarket shelf.