
The historic promise of the American restaurant franchise—the ability for an individual to own a business with the safety net of a national brand—is undergoing a fundamental and potentially irreversible transformation. For decades, franchising served as the backbone of the U.S. middle class, shaping the nation’s physical geography and political economy. However, a new era of consolidation, driven by sophisticated technology and massive capital requirements, is shifting the balance of power toward a new class of "mega-franchisees" and corporate entities, leaving the traditional "mom-and-pop" operator in the shadows.
Main Facts: The Erosion of Franchisee Autonomy
The traditional value proposition of franchising is built on mitigated risk. By paying royalties and following a corporate playbook, operators gain access to established supply chains, national marketing, and proven operating procedures. Historically, this led to higher survival rates for franchised units compared to independent restaurants.
However, experts now warn that this model is being hollowed out. According to data from Kristy Hall, senior vice president of specialty franchise lending at Bank of America, the industry is witnessing a dramatic concentration of ownership. Currently, approximately 19% of franchisees control 60% of all franchised units in the United States. This shift suggests that the "small business owner" image often projected by the industry is increasingly a relic of the past.
The modern franchisee faces a trifecta of pressures:
- Technological Surveillance: Advanced AI and POS systems have granted franchisors granular, real-time control over daily operations, effectively turning independent owners into de facto middle managers.
- Capital Intensity: Rising real estate costs and interest rates have made it nearly impossible for single-unit operators to expand, favoring well-capitalized "MUMBOs" (Multi-Unit Multi-Brand Operators).
- Performance Divergence: A widening gap has emerged between "A-tier" brands (like Chick-fil-A and Dunkin’) and struggling "C-tier" brands (like Subway and Pizza Hut), where stagnant sales prevent operators from reinvesting in their stores.
Chronology: From Post-War Boom to the Post-2022 Reality
The trajectory of the franchise model can be divided into three distinct eras:
The Golden Age (1950s–1990s)
Following World War II, franchising exploded as brands like McDonald’s and Kentucky Fried Chicken utilized the interstate highway system to expand. During this period, the model was largely decentralized. Technology was primitive, meaning franchisors could not monitor a kitchen in Des Moines from a headquarters in Chicago. This gap in oversight provided franchisees with significant operational autonomy.
The Digital Shift (2000s–2020)
The introduction of interconnected Point-of-Sale (POS) systems and third-party delivery platforms began to bridge the information gap. Franchisors started mandating specific technology stacks, ostensibly to improve efficiency, but also to harvest data. During this time, brands like Dunkin’ began a conscious pivot away from single-unit owners toward larger, professionalized management groups.
The Great Divergence (2022–Present)
The landscape shifted violently following the COVID-19 pandemic. According to John Gordon, principal of Pacific Management Consulting Group, 2022 was the last "good year" for the average franchisee. Since then, the Federal Reserve’s interest rate hikes have made debt-financed expansion prohibitively expensive for small players. Simultaneously, the "A-tier" brands have accelerated their growth, while "C-tier" brands have entered a cycle of unit closures and bankruptcy filings.
Supporting Data: The Metrics of a Divided Industry
A deep dive into the Franchise Disclosure Documents (FDDs) of 30 major privately held chains reveals a stark reality of "winners take all."
- Growth Concentration: The top three fastest-growing chains—Cinnabon, Dunkin’, and Chick-fil-A—accounted for a staggering 41% of all net unit growth in 2025 within the analyzed dataset.
- The Subway Contraction: Subway, once the gold standard for the mom-and-pop model with over 20,000 units, lost 729 locations in a single year. The brand is now aggressively pursuing multi-unit operators to stabilize its footprint.
- The "MUMBO" Scale: Entities like the Flynn Group now operate nearly 3,000 locations across eight different brands, including Wendy’s and Taco Bell. Their scale often rivals that of the national brands they represent.
- Financial Thresholds: Analysts suggest that a unit must now generate between $1.5 million and $1.7 million in annual sales just to remain viable for the mandatory remodels and technology upgrades required by corporate headquarters.
The Tech Takeover: "Patty" and the End of Independence
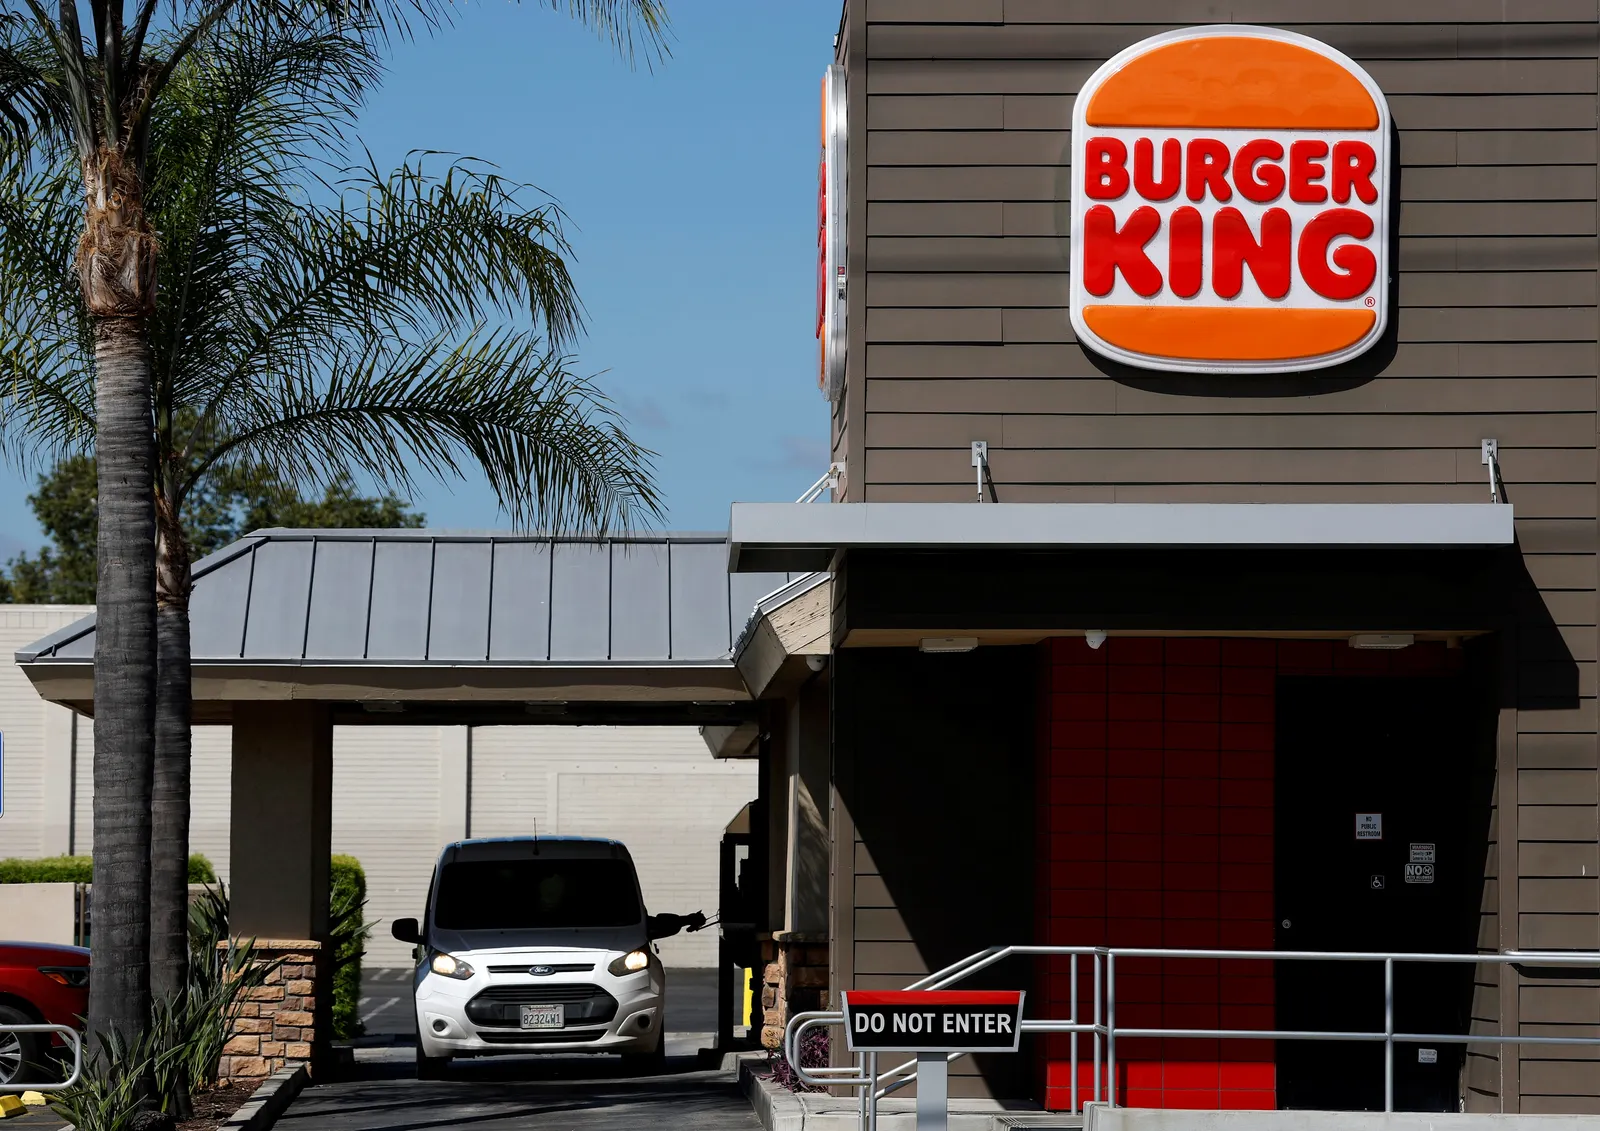
One of the most contentious shifts in the industry is the use of Artificial Intelligence to monitor labor. Burger King is currently rolling out "Patty," an OpenAI-powered voice assistant designed to monitor drive-thru interactions. While the brand pitches Patty as a tool for "coaching" and throughput, labor economists see it differently.
"The degree of [franchisor] control has risen across basically every dimension," says Marshall Steinbaum, an economist who recently co-authored a paper on the balance of power in franchising. He argues that because technology now allows for "up to the minute" monitoring of every cash register, the legal distinction between a franchisee and a corporate employee is blurring.
This sentiment is echoed by Brian Callaci of the Strategic Organizing Center, who notes that franchisors now have the "information richness" to intervene in day-to-day decisions that were once the sole province of the owner. A recent lawsuit involving Pizza Hut’s "Dragontail" AI system highlights the risks: an operator claimed the system’s delivery algorithms actually increased ticket times and stripped him of the ability to manage his own driver pool.
Official Responses and Expert Insights
Industry leaders and financial experts offer a nuanced, albeit sobering, outlook on these changes.
The Lender’s Perspective:
Mark Wasilefsky, head of TD Bank’s restaurant franchise finance group, admits that the "little guy" is being boxed out. "If you want someone to open 50 stores for you, you’ve got to find somebody who’s done that before and knows what they’re doing," Wasilefsky said. He notes that while large franchisees (MUMBOs) are safer bets for banks, they can also become a headache for franchisors. If a franchisee owning 400 out of 1,000 units threatens to revolt over royalty hikes, they have significantly more leverage than a single-unit owner.
The Corporate Support Argument:
Kristy Hall of Bank of America maintains that technological intervention is a necessity in a high-cost environment. "Franchisors that embrace technology thoughtfully will be better positioned to support franchisees and meet evolving customer expectations," she notes. From this perspective, the loss of autonomy is a fair trade for the survival of the brand in a competitive market.
The Economic Critique:
Ulrich Atz, an assistant professor at Bocconi University, points out that the legal structure of franchise contracts has become increasingly restrictive. Non-compete clauses and mandatory vendor requirements mean that even if a franchisee is legally an independent business owner, they often lack the fundamental rights of one. "Depending on your contract… it may also feel like you’re basically an employee," Atz warns.
Implications: The Future of the American Landscape
The consolidation of the restaurant industry into the hands of a few dozen mega-operators and high-performing brands carries significant implications for the American economy and local communities.
1. The Death of Local Touch
As MUMBOs take over, the "local touch" of a restaurant owner who lives in the community and knows the customers is being replaced by professional management firms headquartered states away. While this may improve operational consistency, it often results in a loss of community investment and local philanthropic support.
2. The Real Estate Vacuum
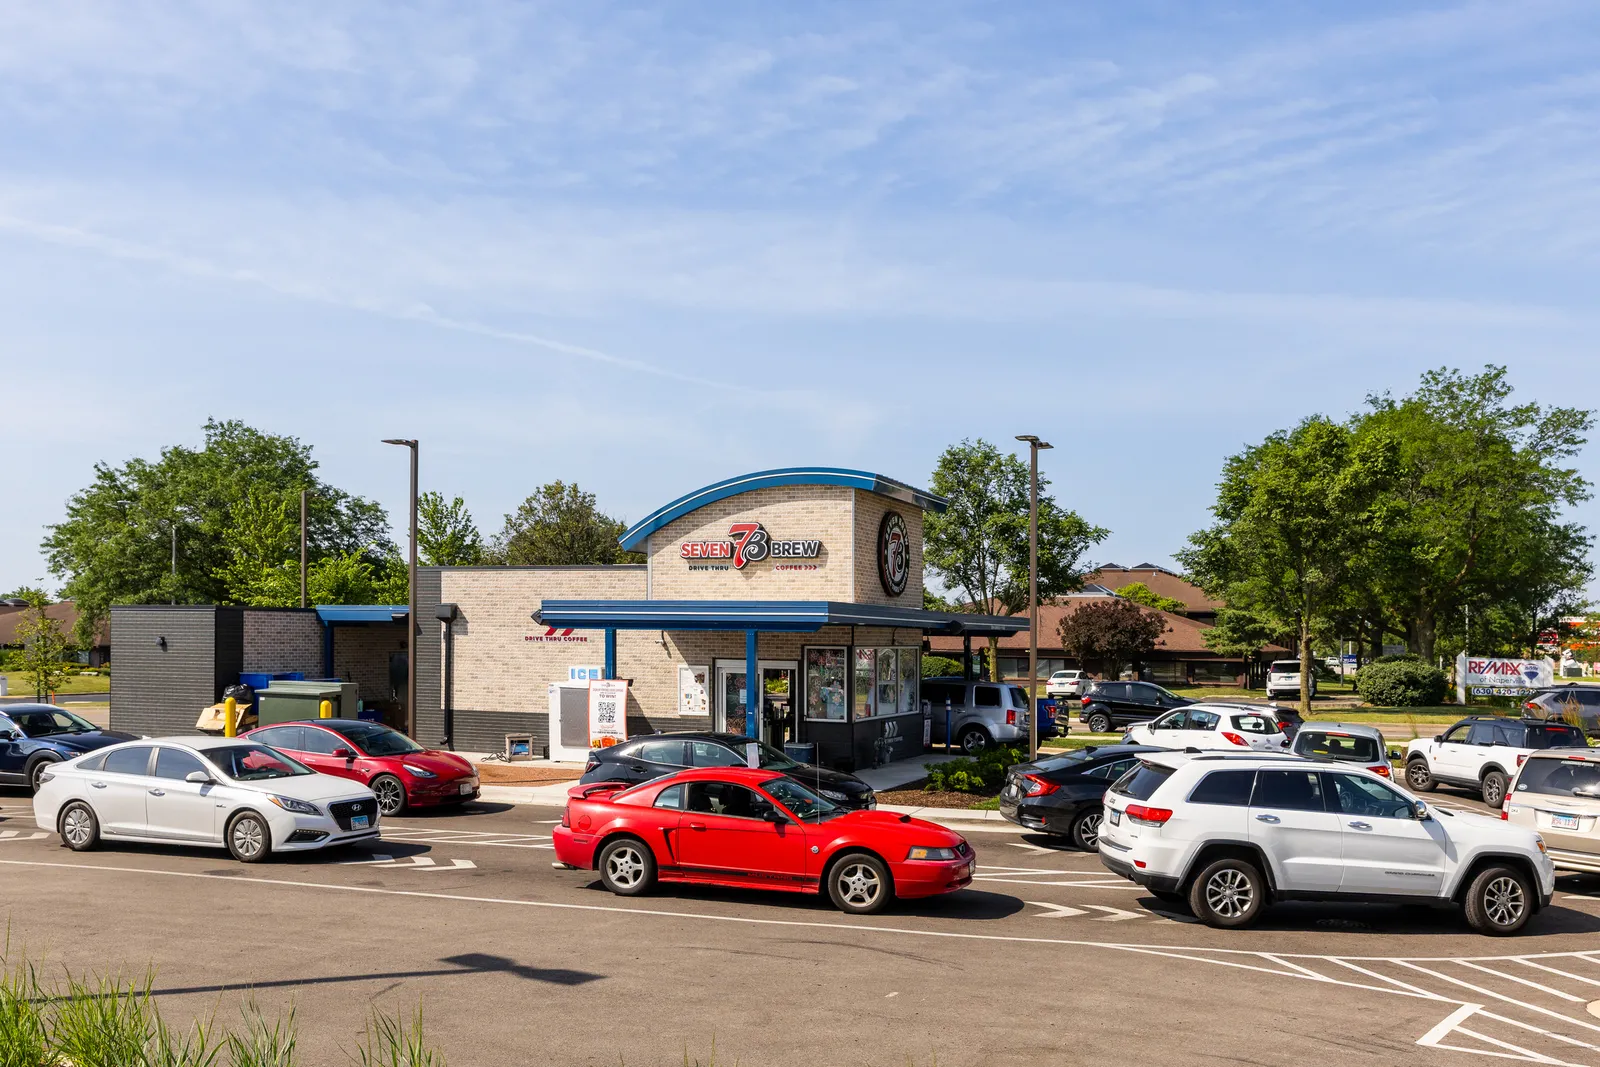
The struggles of "C-tier" brands like Hardee’s, Arby’s, and Sonic are creating a glut of "second-generation" restaurant real estate. Large, well-capitalized players are "scooping up" these sites to redevelop them for high-growth brands like 7 Brew. This creates a cycle where the rich brands get richer, and the struggling brands find it impossible to recapitalize or remodel their aging units.
3. A Two-Tiered Labor Market
As technology like Burger King’s "Patty" becomes standard, the role of the restaurant worker is also changing. Workers are increasingly managed by algorithms rather than humans, which could lead to higher turnover and a further dehumanization of the service industry.
4. The Exit of the Small Investor
The barrier to entry for franchising is no longer a modest savings account and a strong work ethic. It now requires deep institutional backing or private equity. As Hall predicted, the industry’s consolidation will continue as older, single-unit operators exit the market, unable to keep up with the "arms race" of technology and remodeling mandates.
In conclusion, the American restaurant franchise is no longer a monolith. It has split into two worlds: a high-speed, high-tech corporate engine powered by massive multi-unit groups, and a dwindling collection of struggling independent operators fighting against rising costs and eroding control. For the "little guy," the window of opportunity is not just closing—it is being redesigned for a different class of owner entirely.