
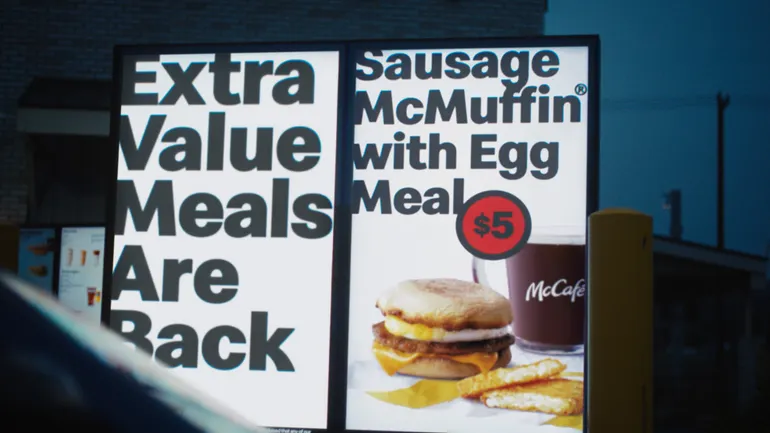
The aggressive price-cutting strategies that defined the quick-service restaurant (QSR) landscape in 2024 are reaching a quiet, yet definitive, conclusion. For much of the year, industry titans like McDonald’s, Wendy’s, and Burger King were locked in a "race to the bottom," attempting to lure inflation-weary consumers with $5 meal deals, buy-one-get-one offers, and deep discounts. However, as third-quarter earnings reports and analyst post-mortems emerge, the verdict is clear: the deep value war is over, and nearly every combatant has emerged bruised.
Market analysts and industry executives are now signaling a strategic pivot. The focus is shifting away from "deep value"—unsustainable price slashing that erodes profit margins—toward "perceived value," which emphasizes product quality, menu innovation, and brand loyalty.
Main Facts: The Failure of the Discount-Centric Model
The primary objective of the 2024 value wars was simple: drive foot traffic. QSR chains hoped that by offering headline-grabbing low prices, they could recapture lower-income consumers who had begun pulling back on discretionary spending. However, the data suggests this gamble largely failed to pay off.
The Margin-Traffic Paradox
According to Peter Saleh, Managing Director and Restaurant Analyst at BTIG, the deep discounting strategy resulted in a "muted" improvement in restaurant margins. While some chains saw temporary blips in customer counts, they were often offset by a decrease in the average check size. Consumers were coming in for the $5 deals but eschewing the higher-margin add-ons like shakes, desserts, or premium sides.
The "Deep Value" Verdict
Saleh’s October report provides a stark assessment: "While we don’t expect any of the quick-service operators to abandon value, we think the deep value war is over, and all have lost." The industry found that price-centric offers did not generate the sustainable traffic gains needed to compensate for the lower profit-per-transaction. Instead, many chains faced weaker margins and stagnating stock prices.
The Shift to Quality
The industry is now moving toward a "Gold Standard" approach. This involves marketing the superiority of the ingredients—such as fresh beef, hand-breaded chicken, and customizable options—rather than just the low cost of the meal. The goal is to convince the consumer that while they may pay a dollar or two more, the quality of the experience justifies the expense.
Chronology: From Aggressive Discounting to Strategic Retreat
The evolution of the 2024 QSR strategy can be traced through three distinct phases: the Escalation, the Realization, and the Pivot.
Phase 1: The Escalation (Early to Mid-2024)
As inflation remained sticky and consumer sentiment soured, major players launched aggressive national campaigns. McDonald’s introduced its much-touted $5 Meal Deal, Wendy’s leaned into its "Biggie Bag" promotions, and Burger King revitalized its value menu. The industry was in a defensive crouch, attempting to protect market share from independent restaurants and grocery stores.
Phase 2: The Realization (Summer 2024)
By August, the cracks in the strategy became visible. McDonald’s leadership admitted that its "$3 and Under" platform failed to gain the expected traction. Internal friction also emerged; approximately one-third of McDonald’s franchisees reportedly failed to execute the value platform according to plan, leading the corporate office to terminate national advertising for the program prematurely. Similarly, Wendy’s CEO Bob Wright characterized certain value deals as "complex" and "value diluting."
Phase 3: The Pivot (Q3 2024 and Beyond)
In the most recent quarter, the narrative shifted during investor presentations. McDonald’s Investor Day focused on "menu innovation" and "upgrading the burger experience" rather than price-point marketing. Burger King found success not through cheaper food, but through improvements to its flagship Whopper. Meanwhile, fast-casual players like Cava began to pull ahead by maintaining consistent pricing and a "health-conscious" image, proving that consumers were willing to pay for perceived quality.
Supporting Data: Winners, Losers, and Margin Realities
The shift in strategy is backed by hard numbers from across the sector, highlighting a divide between those who competed on price and those who competed on brand strength.
- McDonald’s Franchisee Friction: The failure of the $3 platform was partly operational. With roughly 33% of franchisees struggling to maintain profitability under the deep-discount model, the unified national marketing front crumbled.
- Burger King’s Quality Dividend: Burger King’s focus on the "Whopper" and updated chicken nuggets helped it post record-breaking comparable sales in Q2, outperforming its burger-segment peers. This suggests that product-focused marketing was more effective than pure price-slashing.
- The Domino’s Ticket Trade-off: Domino’s reported a rise in order counts in Q3, but a corresponding drop in average ticket prices. While their "Best Deal Ever" promotion (including Stuffed Crust) drove trial, the challenge remains converting those "deal-seekers" into full-price customers.
- The Fast-Casual Edge: Cava is expected to post same-store sales growth of over 3% for Q3. Notably, Cava has priced its menu below the rate of inflation since 2019. By maintaining a smaller price gap between QSR and fast-casual, Cava has successfully captured "trade-down" traffic from casual dining and "trade-up" traffic from traditional fast food.
- Shake Shack’s Digital Strategy: Shake Shack utilized targeted data analytics to offer specific promos (e.g., free Sunday chicken sandwiches with a $10 purchase) via its app. This allowed them to drive frequency and second visits without devaluing the brand through broad, national price cuts.
Official Responses: Insights from the C-Suite and Analysts
The rhetoric from industry leaders confirms that the era of "anything for a buck" is giving way to a more disciplined financial approach.
Peter Saleh (BTIG Analyst):
"We are optimistic that fewer, less frequent deep discounts will result in higher margins as the prior strategy degraded margins with little to no offsetting traffic gains." Saleh emphasizes that the "Gold Standard" of menu items is the new battleground.
Bob Wright (Wendy’s CEO):
Wright noted that while Wendy’s is still testing price-specific offers, such as the $7.99 Dave’s Single Meal, the company is wary of "value dilution." The focus remains on the "Fresh, Never Frozen" brand promise, which provides a competitive moat that price alone cannot build.
Joe Jordan (Domino’s CEO):
Jordan signaled that as competitive pressures from other chains’ value wars subside, Domino’s may pull back on its own discounting. "As [competitive] pressures subside, we can potentially lessen some of that value… we’re working on more targeted promotions to customers to drive that item per order up over time."
Sharon Zackfia (William Blair Analyst):
Zackfia points to the resilience of brands like Dutch Bros and Jersey Mike’s, which have taken "as little price as possible" while maintaining high quality. She notes that for brands like Cava, the value proposition is tied to "extensively customizable" menus that appeal to health-conscious consumers.
Implications: The Future of the QSR Experience
The end of the deep value wars has significant implications for the restaurant industry, the consumer, and the broader economy.
1. The Death of the "Dollar Menu" Mentality
Consumers should expect the permanent disappearance of the "Dollar Menu." The new floor for a "deal" in the QSR space appears to be the $7 to $9 range. While this is higher than the historical norm, chains will attempt to justify the cost through better ingredients, larger portions, and more reliable service.
2. Digital Personalization over National Discounts
The future of value is digital. Instead of offering a $5 meal to everyone, chains will use app data to offer a $5 meal only to the specific customer who hasn’t visited in three weeks. This "surgical discounting" protects margins by ensuring that full-price customers continue to pay full price, while price-sensitive customers are incentivized to return.
3. The Rise of the "GLP-1 Consumer"
As mentioned in McDonald’s Investor Day, the industry is beginning to account for consumers using GLP-1 weight-loss medications. These consumers typically eat smaller portions and are more focused on protein quality than caloric density. The pivot toward "hand-breaded chicken" and "premium burgers" aligns with this demographic shift, where quality is prioritized over quantity.
4. Convergence of QSR and Fast Casual
The lines between fast food (McDonald’s, Wendy’s) and fast-casual (Cava, Shake Shack) are blurring. As QSR prices rise to accommodate better ingredients, they are entering the price territory of fast-casual. This creates a high-stakes environment where QSRs must prove their "Gold Standard" quality can compete with the perceived freshness of more premium brands.
5. Labor and Operational Efficiency
With deep discounting off the table, chains will look to drive profitability through operational efficiency rather than sheer volume. This includes investments in AI-driven drive-thrus, automated kitchens, and simplified menus that reduce labor costs. By making the kitchen more efficient, chains can maintain margins without having to resort to the "value wars" that defined the struggling start of 2024.
In conclusion, the QSR industry has learned a difficult lesson: in a high-cost environment, you cannot discount your way to long-term prosperity. The focus has firmly shifted from the price on the marquee to the quality in the bag.